Executing on Tax Loss Harvesting for End Of Year
I am sure a large amount of people are just like me wondering what, if anything, they should do as the year closes out to take full advantage how much you owe in taxes. I know this is the first year I have learned about the Financial Independence movement and I am excited to document what I am doing so I can look back on it a few years from now and thinks of many mistakes I made.
Step 1: Look at all my taxable accounts to see how everything has performed for the year. This has been a terrible end of the year for the stock market, BUT this is exactly what I was hoping would happen early on in my path to financial independence. The more I continue to dollar cost average and continue purchasing index funds while the market goes down, the more shares I will buy.Account 1: Vanguard Holdings
Now let’s look at how the actual accounts did to see if we have any room to do some tax optimization!
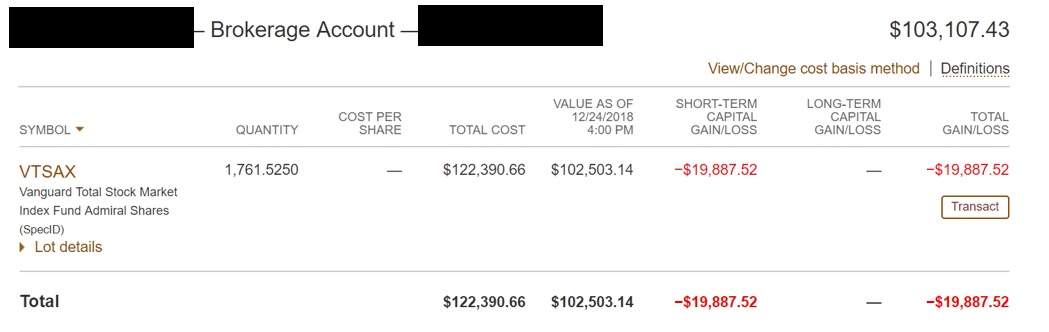
Well that is a part of the game. Total losses for first taxable account: -$19,887.52
Now time to look at my E Trade account:One of the biggest mistakes I made over the course of my investing has been getting into BitCoin. Looking back, I was a dumb and naïve young investor and I have tried to turn it around for the better. I have sold all my shares of the GBTC, but unfortunately lost over $8k in the stock…this isn’t to mention what I lost in actual purchasing of Bit Coin.
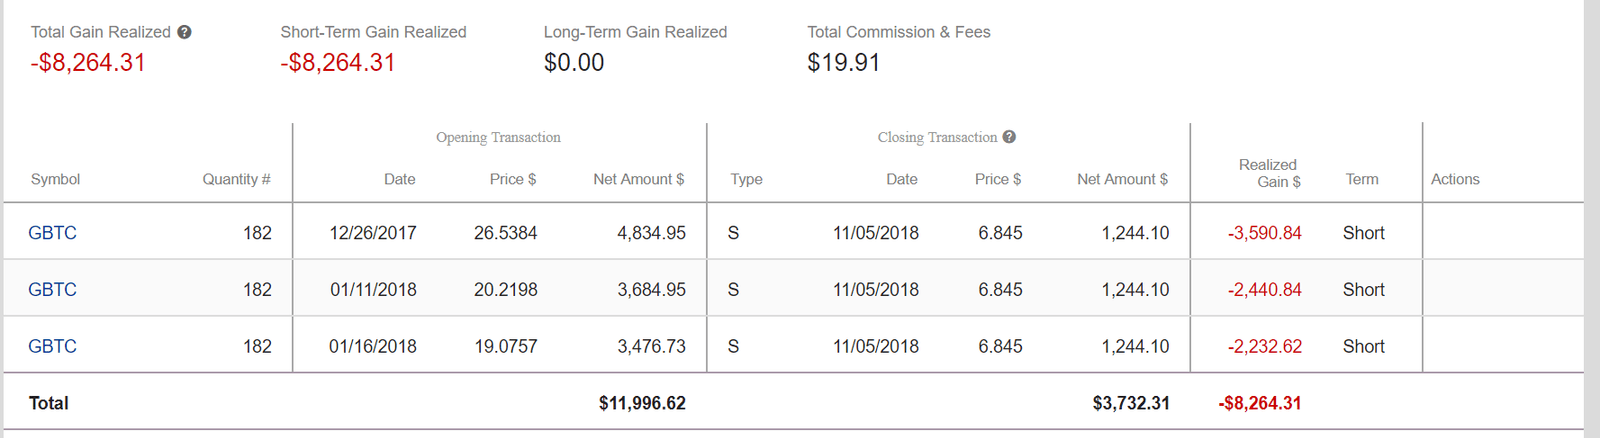
Now to look at my current positions on my E-Trade account:
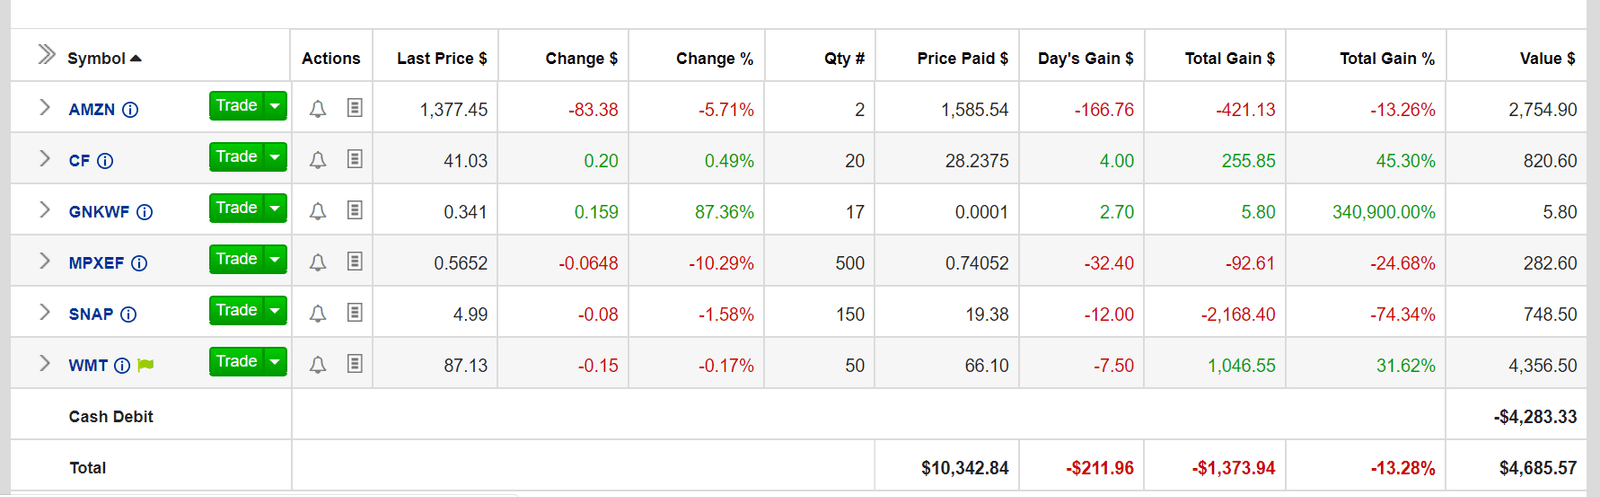
The only stocks that I am going to be able to sell and re-buy to increase my Cost Basis are going to be CF (+$255.85), GNKWF (+$5.80), and WMT (+$1,046.55).
- Total Gains: +$1,308.20
- Total Losses: -$10,525.32
| Account | Gains/Losses |
| Vanguard | -$19,887.52 |
| E-Trade | -$9,217.12 |
| Total | -$29,104.64 |
Selecting all the available shares from my VTSAX taxable account. Note I have setup my account to be able to sell by individual times purchased in order to better harvest gains/losses.
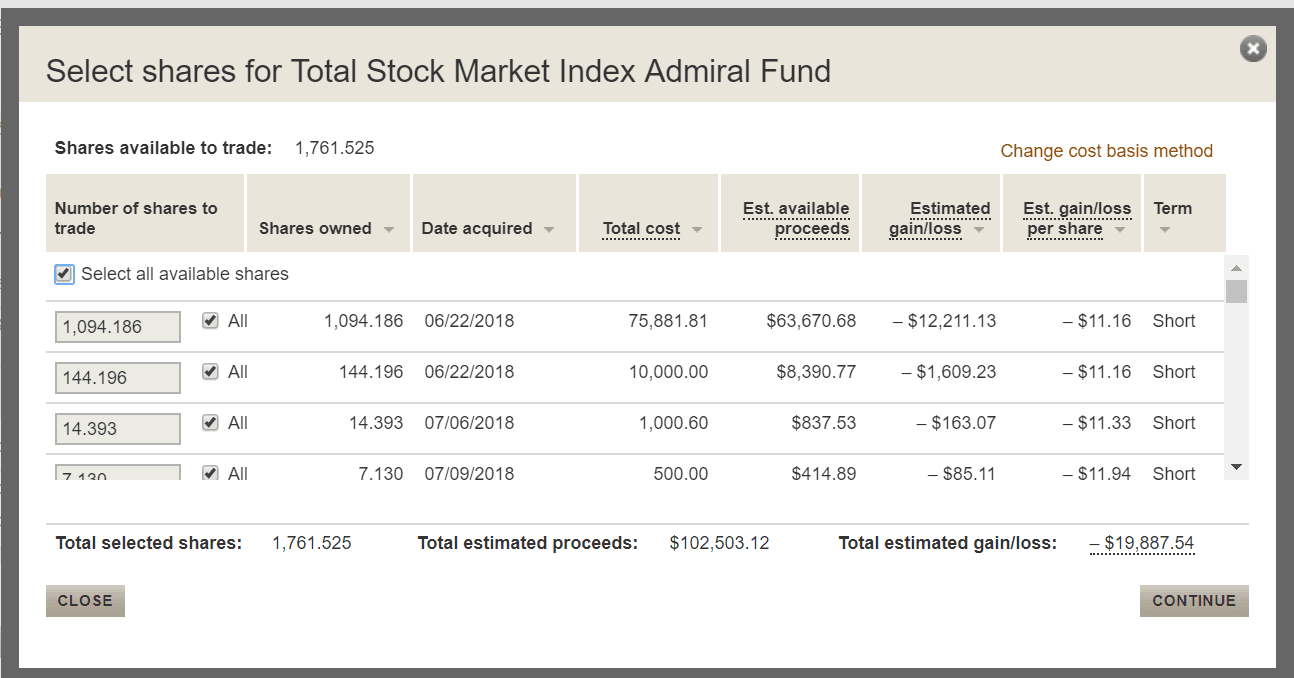
Moving investment to VLCAX
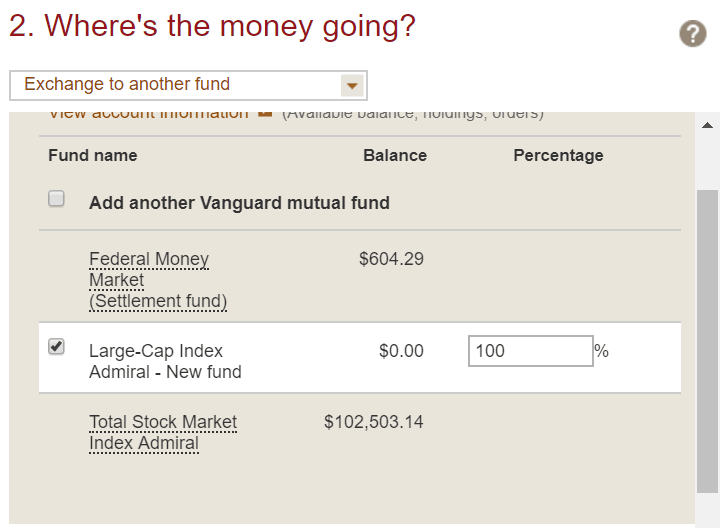 Step 3: Purchase back the VTSAX fund after 31 days to ensure it isn’t considered a wash sale. Since today is Christmas and the markets are closed, the actual purchase of the fund will happen on 12/26 meaning that I can purchase the shares back on 1/28/19. This will ensure I can take advantage of tax lost harvesting.
Step 4: Coming home for the holidays, I found out that I also have a large amount of bonds relatives purchased for me years ago. After doing some research I found that bonds are treated as capital gains if you sell them before the full maturity date. Since I have so much in losses that I can harvest, I can offset some of the losses by all the gains from the bonds. This is the perfect year to do this because I will still have losses after accounting for the interest earned on the bonds. Below is a snapshot of the bonds I have. I found the estimated value of the bonds at this website by putting in the bond number and issue date: https://www.treasurydirect.gov/BC/SBCPrice
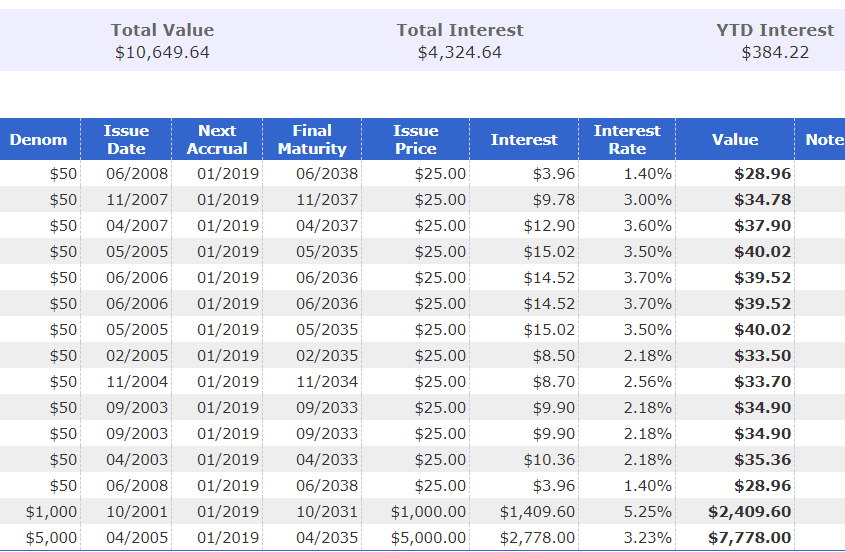
So now I will be able to claim $4,324.64 in gains from interest earned on the bonds.
Full Summary: I know this post has a lot of content in it so I am going to do a really high level overview of what I have done and provide specific numbers- Determined total amount of gains/losses in my taxable accounts
- $19,887.52 in losses from Vanguard
- $9,217.12 in losses from E-Trade
- Looked for a Vanguard fund to purchase after selling my VTSAX to prevent a wash sale. Landed on purchasing VLCAX.
- Sell any taxable account stocks that have increased in value from my E-Trade account
- I will end up selling and re-purchasing CF (+$255.85), GNKWF (+$5.80), and WMT (+$1,046.55) for total gains of $1,308.20
- Sell positions in bonds I currently hold to harvest gains of $4,324.64
| Accounts | Gains/Losses |
| Vanguard | $ (19,887.52) |
| E-Trade | $ (9,217.12) |
| Bonds | $ 4,324.64 |
| Total | $ (24,780.00) |
- Able to reduce taxable income by $3,000 for this year based off current tax limitations. Since I am in the 24% tax bracket, this will save me $720 in taxes this year
- I will be able to carryover $27,780 of losses going into the future so this will be able to save me more money in the future. I think I will be in the 35% tax bracket for next year, so if I max out $3k/year then I will be able to take the max amount of losses for the next 9 years. This means I would end up saving $1,050 per year for the next 9 years totaling up to $9,450!
Let me know what you think and how you are going to crush the game in taxes closing out this year!